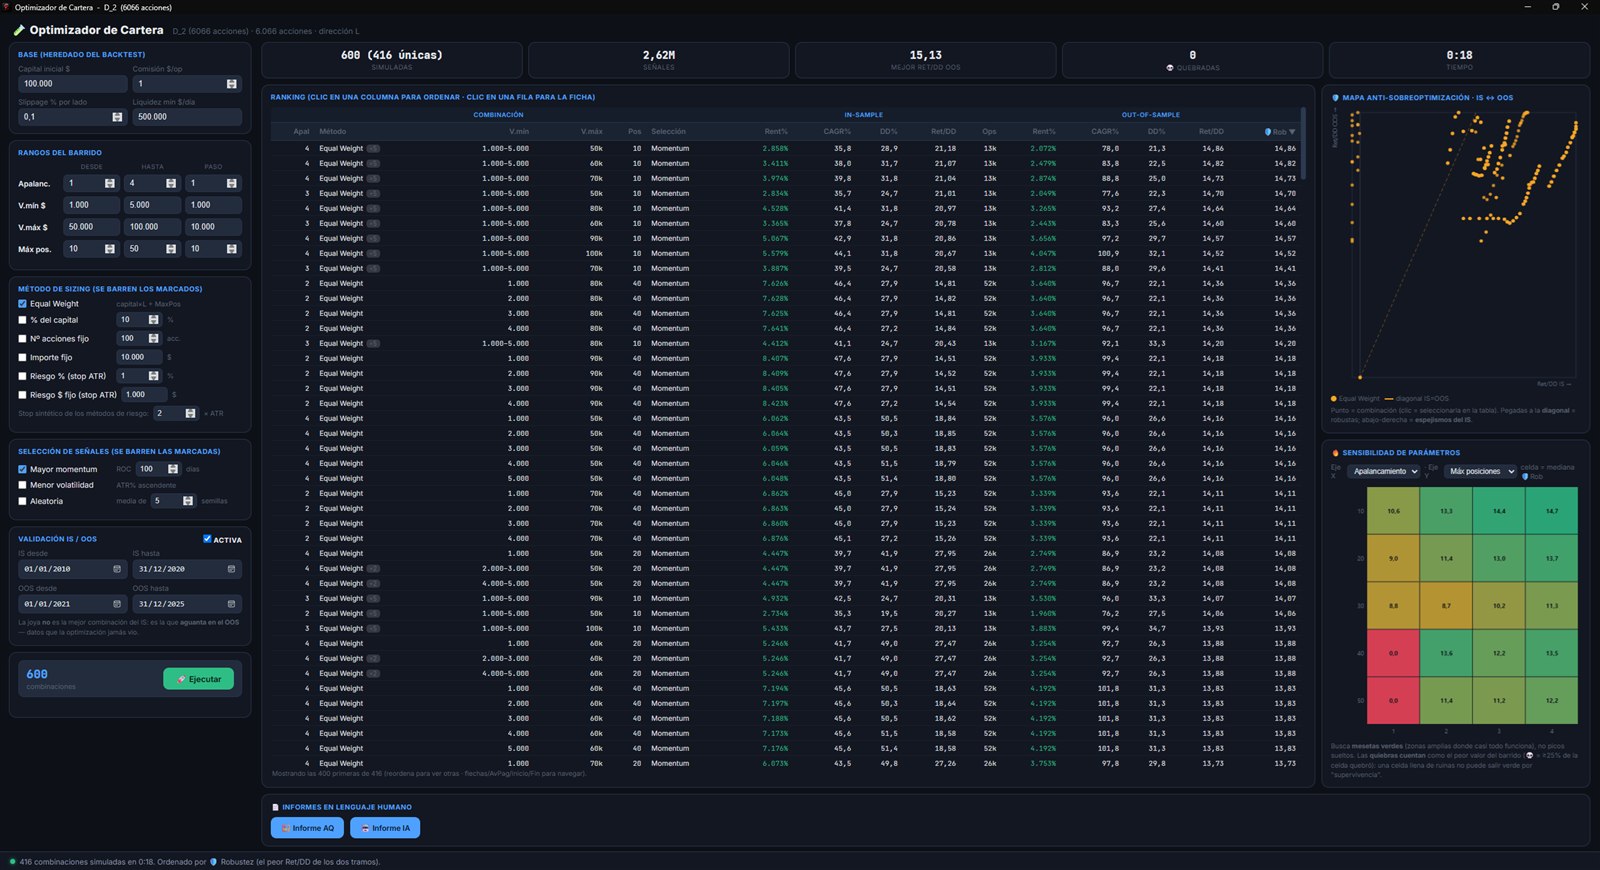
The same strategy can make you rich or ruin you — the difference is position size. The Capital & Risk lab turns sizing from a gut feeling into an engineering decision, with the risk of ruin measured before it happens.

Fixed size, fixed fractional, percent risk, ATR-based volatility sizing, Kelly and more — applied to your actual trade history and compared on the metrics that matter: growth, maximum drawdown, MAR ratio, underwater time. The best sizing method is not a universal truth; it depends on your edge's personality.
Thousands of reshuffled futures of your own trades answer the real questions: what drawdown should I expect? What's the probability of losing half the account? And the verdict panel translates the statistics into sentences a human can act on — no PhD required.
Quick per-trade sizing from account, risk percent and stop distance — futures and stocks.
Seven methods swept over your trade history, with equity and underwater curves for each.
Monte Carlo probability of hitting your personal point of no return — measured, not guessed.
Depth, duration and recovery of every drawdown, across all sizing scenarios.
The numbers, translated: what to expect, what to fear, and when the strategy is being over-leveraged.
Feed it AniQuant backtests or import your real trades from CSV — the lab doesn't care where the trades come from.
30-day free trial, every module included.
⬇ Download AniQuant