One good strategy is a bet. A basket of uncorrelated ones is a business. AniQuant stores your validated strategies, combines them intelligently — and then watches them live, because every edge eventually dies and you deserve to know first.

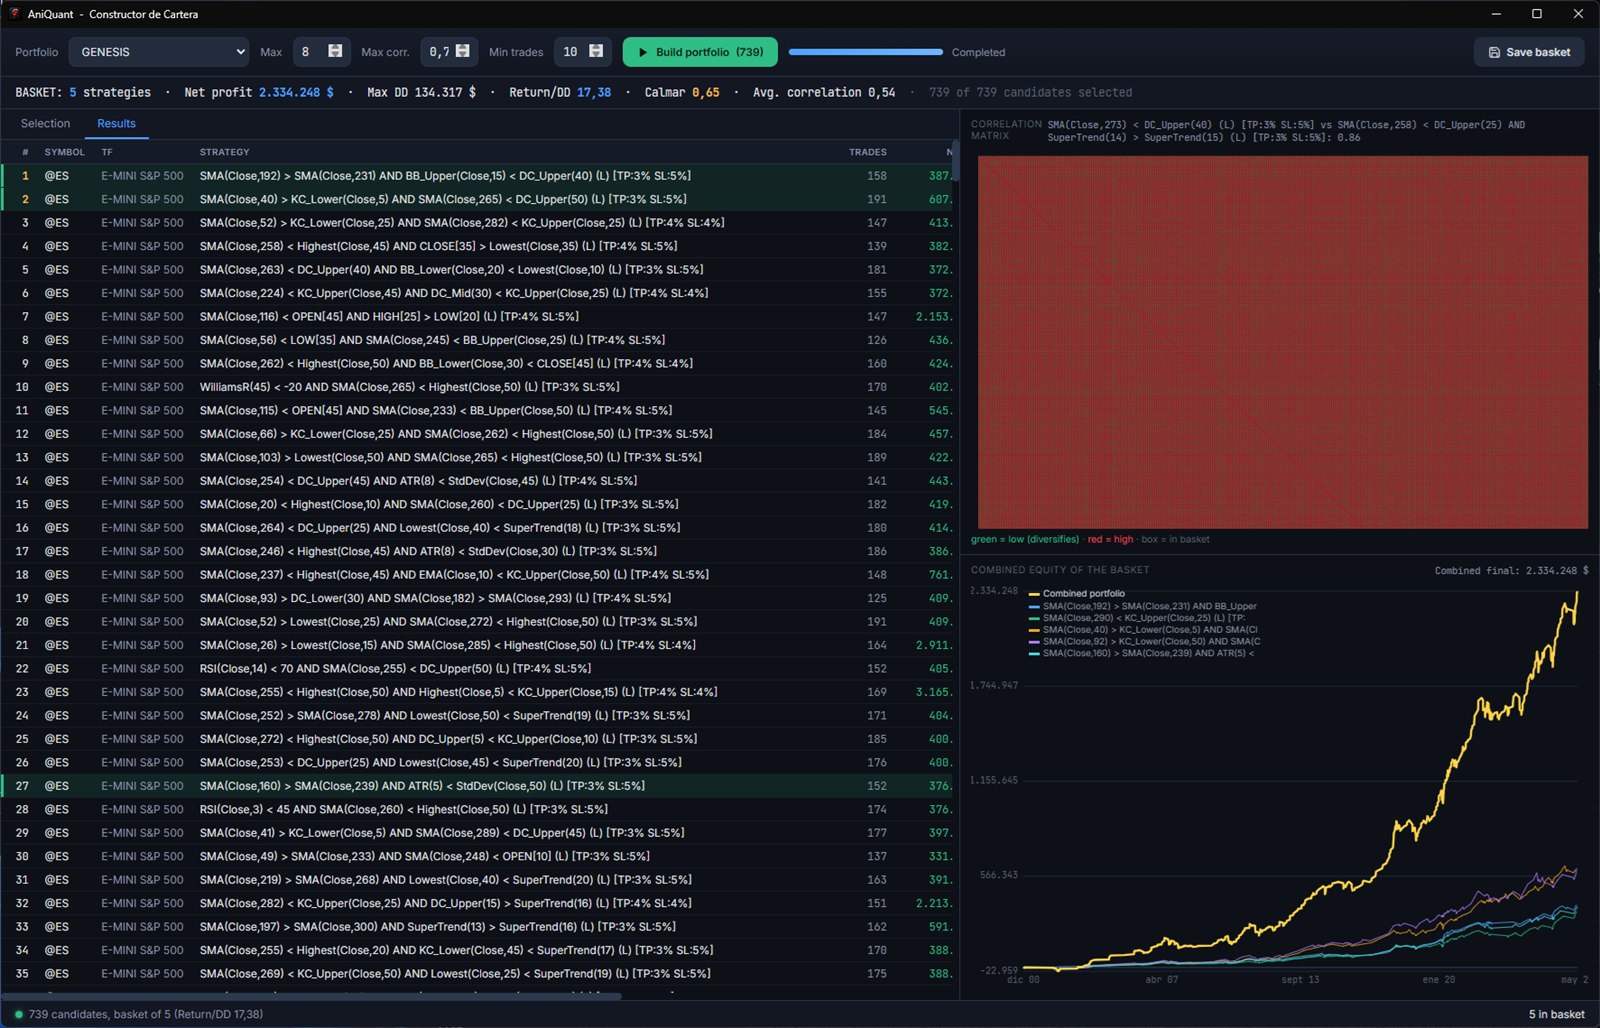
The Portfolio Builder selects strategies the way an allocator would: greedily adding the candidate that improves the basket most while keeping pairwise correlation under your cap. Return/drawdown (Calmar) is computed per strategy and for the combined basket, so diversification is measured — not assumed.
The Edge Health Monitor tracks each deployed strategy's forward equity against its Monte Carlo expectation band. Green, amber, red: performing as expected, degrading, or statistically broken. The hardest discipline in trading — retiring a dead edge — becomes a traffic light.
Store validated strategies with their full identity — rules, parameters, market — and re-test them any time.
Greedy correlation-aware selection with max-positions, correlation cap and minimum-trades constraints.
The portfolio's merged curve with per-strategy contribution — see what each member adds and costs.
Re-run any strategy across N timeframes in one grid — does the edge live only in one clock?
Forward tracking against Monte Carlo bands with a plain traffic-light verdict per strategy.
Massive money-management sweeps over cached signals — leverage, sizing methods and limits, with anti-overfitting views.