Robustness Suite

Where beautiful backtests
go to be questioned

A great historical curve is a hypothesis, not a result. The Robustness Suite is the institutional-grade gauntlet — walk-forward, Monte Carlo, overfitting probability, survival testing — that your strategy must run before it earns your money.

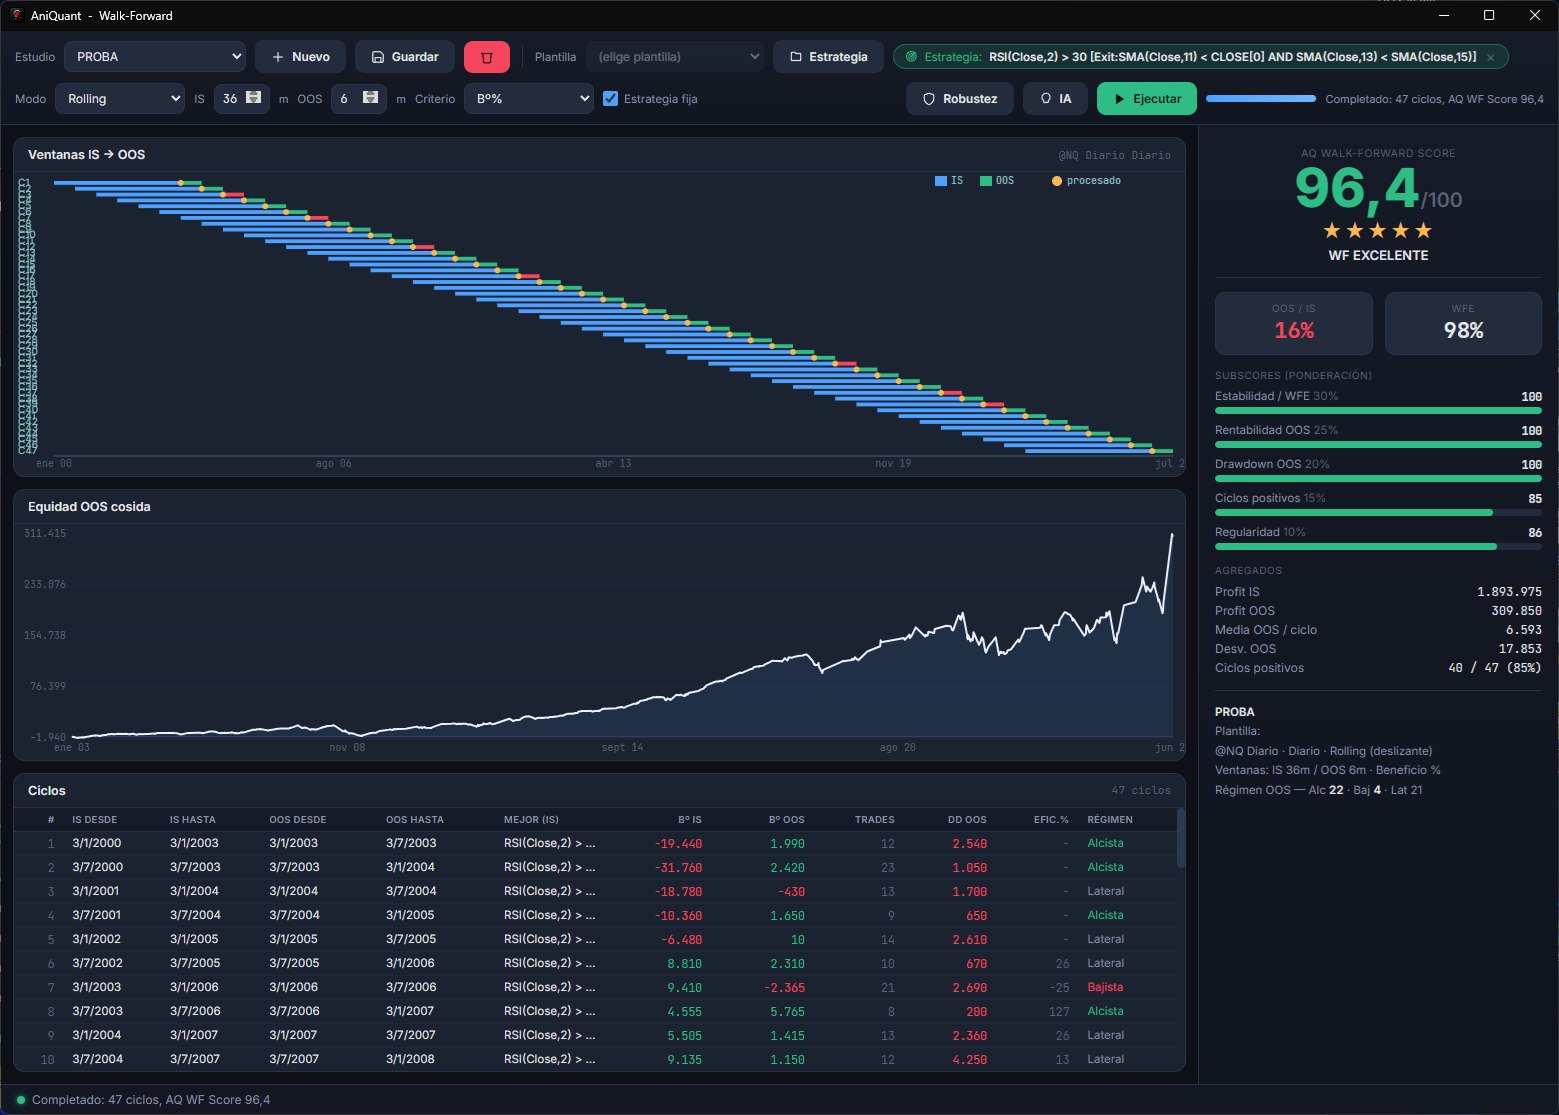
Walk-Forward analysis — rolling IS/OOS windows, stitched OOS equity and AQ WF Score
The question

Would you have found it in time?

Walk-forward analysis answers the only question that matters: if you had re-optimized on the past and traded the result on the unseen future — window after window, for decades — would it have worked? AniQuant re-optimizes each window for real and aggregates it into a weighted AQ WF Score.

The trap

Overfitting has a probability. Measure it.

When you test thousands of variants, the best one is partly best by luck. The PBO/DSR module (combinatorially symmetric cross-validation) estimates how likely it is that your winner is a mirage — before you find out the expensive way.

The gauntlet

Five validators, one verdict

🚶

Walk-Forward

True per-window re-optimization with the AQ WF Score — efficiency, consistency and degradation in one number.

🎲

Monte Carlo

Trade-order shuffling with the percentile on what actually varies: the drawdown distribution.

🧮

PBO / DSR

Probability of backtest overfitting and deflated Sharpe over the entire sweep matrix.

🏥

Survival Test

Six phases of stress into a 0–100 AQ Survival Score: how much abuse can the edge absorb?

🗺️

Sensitivity maps

Parameter-neighborhood heatmaps: a real edge lives on a plateau, not on a needle-peak.

🧾

360° report + Edge DNA

All validators condensed into one AI-written report and a visual robustness ID card with a final confidence grade.

Trust what survives

30-day free trial, every module included.

⬇ Download AniQuant